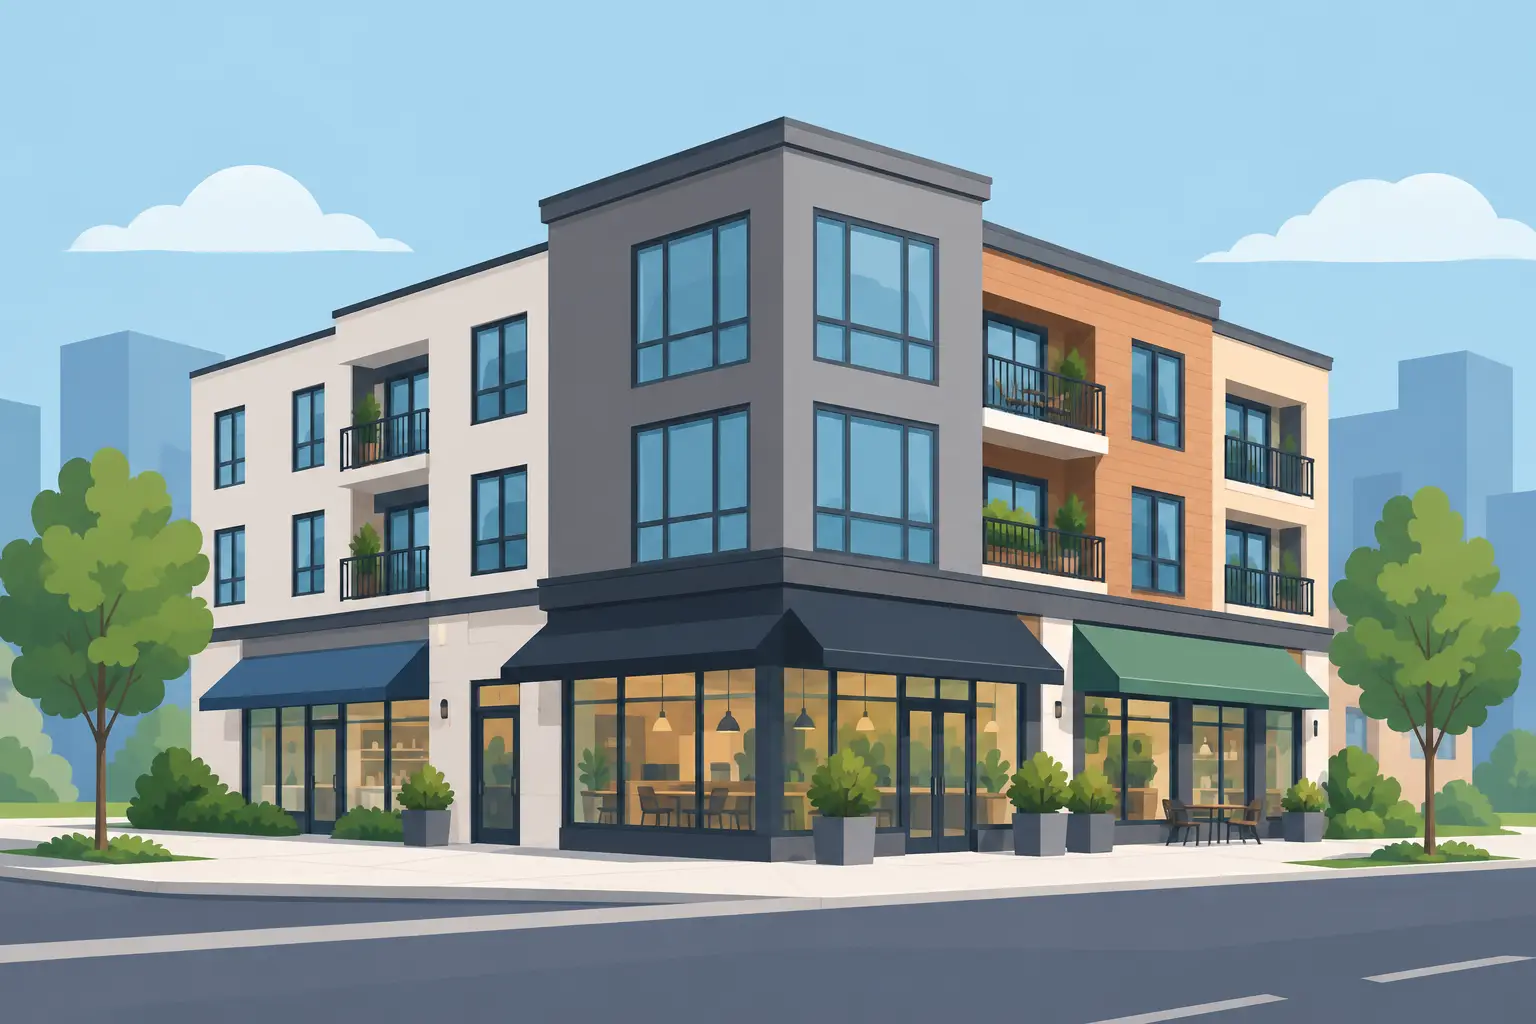
A shopfront with a flat above it can look like a straightforward property purchase. For lenders, it can be anything but straightforward. A mixed use property example often sits between residential and commercial lending rules, which means the right loan structure depends on far more than the purchase price.
For Australian borrowers, this matters when the property is intended as an investment, a place to run a business, a home, or all three. If a major bank has declined the application because the property is partly commercial, the income is non-standard, or the valuation does not fit its policy, there may still be specialist lending options to consider.
What is a mixed use property?
A mixed use property combines residential and commercial uses on one title or within one development. The commercial component may be a retail shop, café, office, medical suite, warehouse showroom or consulting room. The residential component could be a house, apartment, unit or manager’s accommodation.
Common examples include a terrace with a hair salon at street level and a two-bedroom residence upstairs; a suburban medical practice with a self-contained flat; or a small warehouse with an attached caretaker’s dwelling. Some properties are owner-occupied, while others are leased to separate commercial and residential tenants.
The key issue is not simply whether someone can sleep at the property. Lenders look at the zoning, the proportion of floor space used commercially, rental income, lease arrangements, location, valuation and the borrower’s ability to service the debt.
A mixed use property example in practice
Consider a self-employed electrician buying a property in a regional NSW town for $950,000. The building has a ground-floor showroom and office, which he plans to use for his business, plus a three-bedroom residence upstairs where his family will live. The property is zoned for mixed use, the commercial space represents about 45 per cent of the building, and the residence has a separate entrance.
Although the borrower will live there, a lender may not treat this as an ordinary home loan. The business use, commercial zoning and specialist valuation can move the application into commercial property finance or a hybrid policy category. A lender may also want to understand whether the business could continue meeting repayments if trading softens or the premises need repairs.
In this case, the application could be supported by the electrician’s business financials, BAS statements, tax returns, bank statements and evidence of current work or contracts. If the business has strong turnover but taxable income is reduced by legitimate deductions, an alternative-documentation lender may assess income differently from a mainstream bank. That does not remove the need to show repayment capacity, but it can create a more practical path for an established business owner.
The same property would be assessed differently if the shop were leased to another business and the borrower only occupied the residence. The lender would then consider the strength of the commercial tenant, lease term, rental income, outgoings and vacancy risk alongside the borrower’s personal income.
Why the loan type can change
A property being partly residential does not guarantee residential lending. Each lender has its own policy, but the following factors commonly influence the outcome.
Zoning and permitted use
Residential zoning generally suits standard home lending. Mixed-use, commercial, industrial or business zoning can limit the number of residential lenders willing to consider the security. Council approvals and permitted use need to match the actual use of the property. An unapproved residence above a shop can create problems even where the borrower has lived there for years.
Commercial versus residential floor area
Many lenders set limits around the commercial portion of the building or land. A small home office in an otherwise residential house is very different from a large retail tenancy with a compact apartment attached. Floor area, access, parking and the income produced by each component can all affect the classification.
Owner occupation, investment or business premises
Lenders assess risk differently when a borrower lives in the property, runs their own business from it, or relies on tenants to pay rent. An owner-occupied business premises may be assessed against business cash flow. An investment property may be assessed against lease income, vacancy allowances and the applicant’s wider financial position.
Property marketability
If repayment difficulties arise, a lender needs confidence that the security can be sold within a reasonable period. A well-located shop and residence in an active town centre may be more readily marketable than a highly specialised building in a small or remote location. This is one reason valuations are so important for mixed use lending.
Documents that can strengthen an application
A clear, well-prepared application helps a lender understand the property and the borrower from the outset. For a mixed use purchase or refinance, documentation may include the contract of sale or current loan statements, rates notices, council zoning information, building plans, leases, rental schedules and a valuation where available.
For self-employed applicants, lenders may request individual and business tax returns, financial statements, BAS statements, accountant-prepared figures and business bank statements. Alt-doc options can be useful for eligible borrowers whose most recent tax returns do not reflect current trading. Depending on the lender and loan purpose, an accountant’s declaration, BAS history or business activity may help demonstrate income.
If there has been adverse credit, address it directly rather than hoping it will be overlooked. A paid default, prior arrears, Part 9 debt agreement or bankruptcy discharge does not automatically mean finance is impossible. The timing, amount, explanation, current conduct and equity position all matter. Specialist lenders can have different credit policies, but a realistic loan request and complete supporting evidence remain essential.
Deposit, LVR and valuation considerations
The loan-to-value ratio, or LVR, is the loan amount divided by the lender’s assessed value of the property. Mixed use properties can require a larger deposit than a standard residential purchase because their buyer pool is narrower and valuations may be more conservative.
There is no single LVR that applies to every property. A modest commercial element in a strong residential location may attract different terms from a property that is predominantly retail, hospitality or industrial. Loan size, postcode, tenant quality, borrower experience and the purpose of the loan also affect the available options.
Borrowers should also allow for valuation fees, legal costs, stamp duty, possible GST implications and funds for fit-out or repairs where relevant. For business owners, putting every available dollar into the deposit can leave too little working capital after settlement. The best structure is not always the one with the smallest deposit. It needs to leave the business and household with enough room to manage ordinary fluctuations.
Questions to resolve before making an offer
Before signing a contract, confirm the zoning and permitted uses, whether the residential accommodation is approved, and whether any lease is transferable. Ask for outgoings, rent records, details of vacancies and copies of existing agreements. If you intend to operate a business from the premises, consider planning approval, fit-out costs, insurance and whether the location genuinely suits customers, staff and suppliers.
It is also worth checking how the contract handles finance and due diligence. Mixed use lending can involve a more detailed valuation and credit review than a standard home loan. A short finance clause may not provide enough time, particularly where trust structures, SMSFs, company borrowers, overseas income or complex financials are involved.
Finding a pathway when bank policy says no
A mainstream bank decline is often a policy decision, not a final judgment on your ability to buy or refinance. The issue may be the zoning, the commercial percentage, a recent credit event, short self-employment history or the way income has been documented.
Finance Me can assess the full picture, identify lenders that consider mixed use security, and help present the application with the right supporting documents. This is particularly useful where the borrower needs commercial finance, alt-doc income assessment, a refinance to improve cash flow, or a specialist pathway after credit difficulties.
A mixed use property can be a practical way to combine a home, investment and business opportunity. The useful next step is to have the property, income and intended use assessed early, so your finance structure supports the purchase rather than holding it back.