A declined refinance application does not always mean you are stuck with your current loan. For Australians refinancing home loan bad credit, the right path usually starts with a clear assessment of what happened, what has changed, and which lenders can consider your circumstances beyond a standard bank credit score.
You may be paying a high variable rate, facing a fixed-rate expiry, juggling personal debts, or trying to release equity for a legitimate purpose. If you have defaults, missed repayments, a discharged bankruptcy or a Part 9 debt agreement on your record, a major bank may not be the right first option. Specialist lenders assess these applications differently, provided the loan is affordable and the proposed refinance makes financial sense.
Can you refinance with bad credit?
Yes, refinancing may be available with impaired credit, but approval depends on more than the adverse event itself. Lenders want to understand the cause, the timing, the amount involved and your conduct since then. A single paid telecommunications default from several years ago is assessed very differently from recent mortgage arrears or multiple unpaid debts.
Your available equity is also central. Equity is the difference between your property’s value and the amount you owe on it. A lower loan-to-value ratio, or LVR, can give you more lender options because there is a larger buffer in the property. Some specialist products can consider higher LVRs for eligible borrowers, though rates, fees and lending criteria may be stricter.
The lender will also look closely at whether you can service the new loan. That means verifying income, reviewing living expenses, checking existing liabilities and confirming that repayments remain manageable if interest rates rise. Bad credit can narrow the market, but it does not remove the need for a sustainable lending outcome.
What specialist lenders may consider
Mainstream banks often rely on tightly defined credit policy. Specialist lenders can take a more detailed view of the overall file. That does not mean they ignore bad credit. It means they may consider context and evidence that a standard automated assessment does not capture.
For example, an applicant may have fallen behind after illness, a relationship breakdown, a business interruption or a period of reduced work. If the issue has been resolved, debts have been repaid or placed under a formal arrangement, and recent repayment conduct is stable, there may be a refinance pathway.
A lender may consider applicants with paid or unpaid defaults, court judgments, mortgage arrears, discharged bankruptcies and completed Part 9 debt agreements, subject to its policy. Time since the event matters. So does the explanation. The stronger applications show that the original problem is not continuing and that the borrower now has a realistic budget.
Self-employed borrowers can also be well suited to specialist refinancing. A tax return alone may not show the current strength of a business. Depending on the lender and loan type, evidence may include recent BAS statements, business bank statements, accountant-prepared financials, company returns or alternative documentation. The acceptable documents and income treatment vary between lenders.
When refinancing can improve your position
Refinancing should solve a problem, not simply move it to a different lender. It can be useful when it replaces an expensive short-term facility, removes a co-borrower after a separation, consolidates high-interest debts, or gives you time to rebuild your credit while maintaining a home loan.
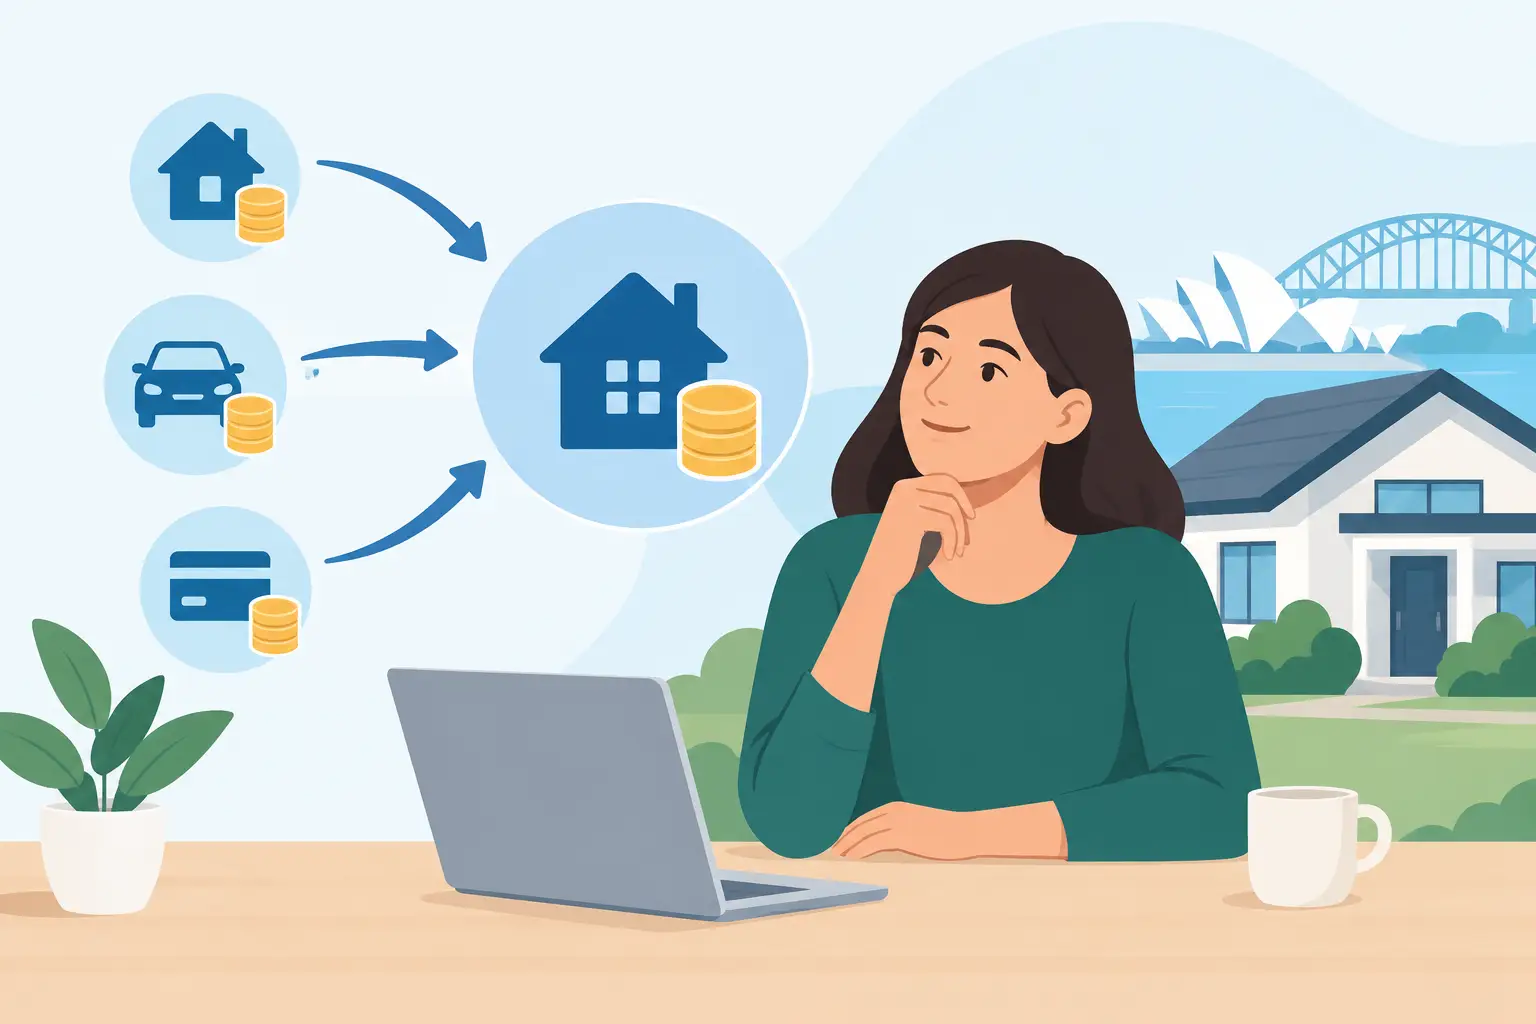
Debt consolidation is a common reason for applicants with adverse credit to refinance. Rolling credit cards, personal loans or overdue accounts into a home loan can reduce the immediate monthly repayment because home loan terms are longer and rates may be lower. However, the debt is then secured against your home. If you only make minimum repayments over a long term, the total interest paid can be substantial.
A sensible structure usually includes a plan to close the consolidated facilities and avoid rebuilding those balances. In some cases, the best result is a refinance now with a specialist lender, followed by a review after 12 to 24 months of clean repayment history. If your credit profile, equity and income improve, a broader range of lenders may become available later.
Documents that strengthen a bad-credit refinance
Preparation matters. Incomplete applications can create delays and make a complex situation appear less clear than it really is. Before applying, obtain a current copy of your credit report and check it carefully. Look for incorrect listings, debts that have been paid but not updated, and enquiries you do not recognise.
You will generally need identification, recent loan statements, rates notices, evidence of income and details of your regular expenses and debts. Employees may provide payslips and bank statements. Self-employed applicants may use BAS statements, business bank statements, financials or other lender-approved income evidence.
For adverse credit, supporting documents are equally important. A paid-default letter, discharge paperwork, a debt agreement completion certificate, correspondence explaining a hardship period, or proof that an outstanding debt has been settled can help the lender assess the full story. Be direct about the issue from the start. A specialist broker cannot place you with every lender, but can identify those whose policies are more likely to suit your position.
The property value and LVR matter
A refinance lender will generally require a valuation of your property. The valuation establishes the security value and helps calculate your LVR. For instance, if your home is valued at $800,000 and the total new loan is $560,000, the LVR is 70 per cent.
Lower LVRs can support a stronger application because the lender is taking on less security risk. At a higher LVR, lenders may require mortgage insurance, a higher interest rate, or additional evidence of income and credit rehabilitation. If you are seeking cash out for debt consolidation, renovations or another purpose, that amount is included in the new loan balance and must still fit within the lender’s maximum LVR.
Do not rely solely on a property estimate you have seen online. A formal lender valuation can be lower or higher than expected, particularly where local sales have changed or the property has unusual features. Build some room into your plans rather than assuming every dollar of equity will be available.
Compare the whole loan, not just the rate
A specialist bad-credit refinance may have a higher rate than a prime bank loan. That can be reasonable if it stops arrears, replaces unsustainable debt, or gives you a workable path back to mainstream lending. It is not reasonable if the fees and repayments leave you worse off without a clear benefit.
Compare the interest rate, comparison rate, establishment fees, valuation fees, discharge costs on your existing loan, ongoing fees and any break costs if you are leaving a fixed-rate loan. Check whether the loan has redraw, an offset account, extra repayment flexibility and restrictions on refinancing again in the near future.
Also ask how long the lender expects you to remain on the product. Some specialist facilities are designed as a longer-term solution. Others may be more appropriate as a stepping stone while you demonstrate reliable conduct. The right answer depends on your equity, income stability, credit history and future plans.
A practical refinancing process
The first step is an honest review of your current loan, credit report, income and property position. From there, a broker can calculate your likely LVR, identify the debts to be refinanced and assess whether your income meets servicing requirements.
Next comes lender selection. This is where specialist experience can make a material difference. Applying to several unsuitable lenders can add unnecessary credit enquiries and frustration. A targeted application presents the explanation for your adverse credit alongside the documents that support it.
Once a lender issues conditional approval, the process may include a property valuation, further document checks and confirmation of payout figures from your existing lender. At formal approval, review the loan documents carefully before settlement. The old loan is then paid out and the new facility begins.
Finance Me works with Australians whose credit history, income type or lending needs fall outside standard bank policy. The focus is not on judging past financial difficulty. It is on finding a realistic loan structure, preparing the evidence properly and helping you understand the commitments before you proceed.
If a refinance is not suitable right now, that is useful information too. Paying down smaller debts, correcting credit-report errors, building a stronger repayment record or waiting for a recent event to age can improve your options. A clear plan is often more valuable than another rushed application.