A cash-out refinance can be a practical reset when equity is tied up in property but your current loan no longer suits your circumstances. The term structure cash out refinance is often used to describe more than simply borrowing extra money. It means arranging the loan, security, evidence of income and purpose of funds in a way a lender can understand and approve.
For a borrower with straightforward PAYG income and a clean credit file, the process may be relatively simple. For a self-employed business owner, someone rebuilding after a credit event, or a borrower using overseas or variable income, the structure matters much more. The right lender and documentation pathway can be the difference between a workable refinance and another bank decline.
What is a cash-out refinance?
A cash-out refinance replaces your existing home loan or investment loan with a new loan for a higher amount. The new lender pays out the current mortgage, and the remaining funds are released to you at settlement or shortly after.
For example, if your property is valued at $900,000 and you owe $450,000, you may have substantial equity. Subject to the lender’s maximum loan-to-value ratio (LVR), servicing assessment and the purpose of the funds, you may refinance to $600,000. After paying out the existing loan and settlement costs, the balance could be available for debt consolidation, renovations, business purposes, an investment deposit or another legitimate need.
The available cash is not based on equity alone. A lender will assess the property valuation, your income, existing commitments, credit history, the proposed loan repayment and how the released funds will be used.
How to structure a cash out refinance
A well-structured application starts with the outcome you need, not a loan product picked at random. The loan should solve a defined problem without creating repayment pressure that becomes harder to manage later.
Start with the purpose of the cash out
Lenders generally want a clear, reasonable purpose for additional funds. Common purposes include consolidating personal debts, paying out ATO debt under an agreed arrangement, funding property improvements, purchasing business equipment, contributing to a commercial venture, meeting family-law settlement obligations or funding an investment deposit.
Some purposes receive closer scrutiny than others. Cash out for business use may require BAS statements, financials, bank statements or a clear explanation of the transaction. Debt consolidation usually requires current payout figures for each liability. If funds are for renovation work, a lender may ask for quotes or a scope of works.
Being specific is helpful. “Personal use” may be accepted by some lenders at lower amounts, but a detailed explanation generally gives a lender more confidence, particularly where the requested cash out is significant or the credit profile is non-standard.
Calculate a realistic LVR, not just the maximum
LVR is the loan amount divided by the property value. It is one of the central decisions in any refinance. A higher LVR may release more funds, but it can limit lender choice, increase pricing and mortgage insurance costs, or make an application harder where there is adverse credit or alt-doc income.
For instance, a borrower may technically have enough equity to refinance at 85% LVR. Yet keeping the loan at 75% or 80% could provide access to a broader lender panel and a more manageable rate. Conversely, some specialist lenders can consider higher-LVR scenarios where the overall application is strong and the reason for refinancing is sound.
The valuation also matters. Do not assume an online property estimate is the amount a lender will use. A lender-ordered valuation can be lower or higher, and that result affects how much cash can be released.
Match the evidence to your income type
Mainstream lenders often prefer payslips, group certificates and stable employment history. Specialist lending offers other ways to assess borrowers who earn income differently.
A self-employed applicant may be able to use BAS statements, business bank statements, accountant-prepared financials or alternative documentation, depending on the lender and loan purpose. Company directors may need to show how business income flows to them personally. Contractors can require contracts, invoices and bank credits. Australians paid from overseas may need to provide foreign payslips, employment contracts, tax returns or bank statements, with lender policy differing on acceptable currencies and income shading.
Alternative documentation is not a shortcut around affordability. The lender still needs to see a credible capacity to repay. It is simply a more appropriate assessment method when standard tax returns do not tell the full story.
Address credit issues early
A late payment, default, discharged bankruptcy or Part 9 debt agreement does not automatically prevent a cash-out refinance. However, it must be explained and placed in context. Lenders will consider when the event occurred, whether it has been paid or discharged, what caused it and how your position has changed.
For example, a business interruption, illness, separation or a one-off period of financial stress may be viewed differently from ongoing unpaid liabilities. Recent conduct matters. Clean repayment history since the event, reduced unsecured debt and a stable income position can strengthen an application.
Trying to minimise or hide a credit issue usually creates delays. A specialist broker can identify lenders that consider adverse-credit applications before a full application is submitted, helping avoid unnecessary enquiries on your credit file.
When debt consolidation is the main goal
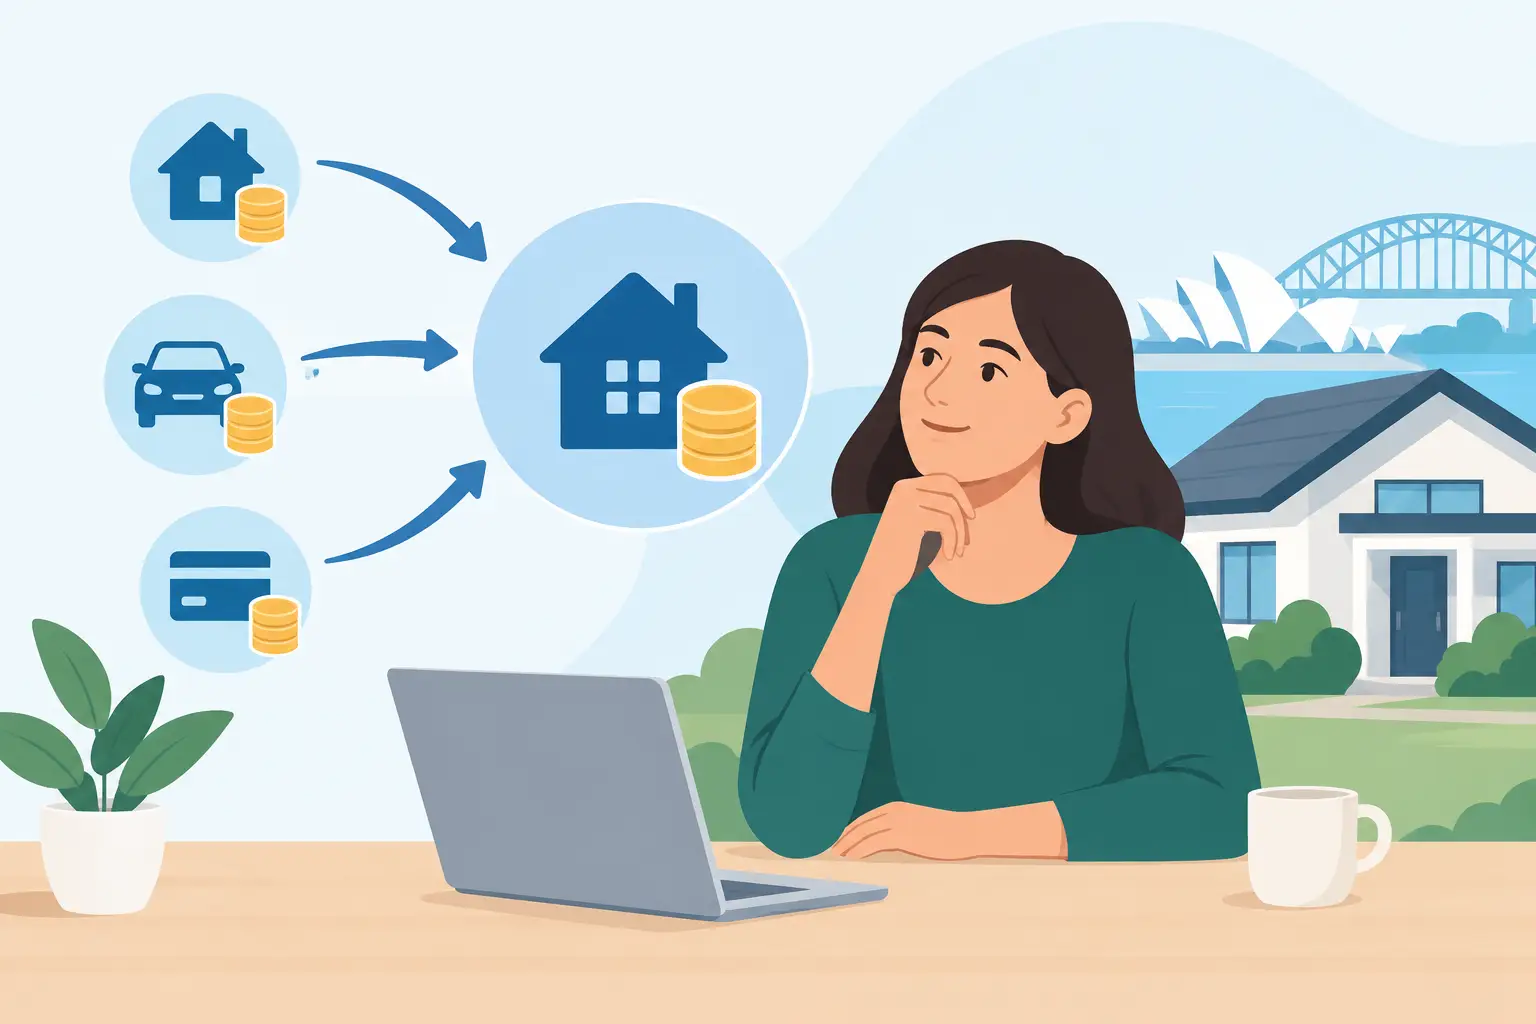
Cash-out refinancing is often used to consolidate credit cards, personal loans, tax debt or other high-cost liabilities into a property-backed facility. The immediate repayment can be lower because the debt is spread over a longer loan term. That can improve cash flow, but it is not automatically cheaper overall.
If you refinance $40,000 of unsecured debt into a home loan over 25 or 30 years, you may pay more total interest unless you make additional repayments. A sensible structure may include a separate split for consolidated debts, with a shorter repayment target or regular extra repayments. This keeps the purpose visible and helps prevent short-term debt from quietly becoming long-term mortgage debt.
The lender will normally require payout letters and may pay creditors directly at settlement. This protects the refinance purpose and ensures the proposed monthly savings are real.
Should the cash out sit in a separate loan split?
Often, yes. A separate split can make the loan easier to manage and explain. You might retain one split for the existing home loan balance and use another for renovation costs, business funding or debt consolidation.
Separate splits can also be useful when the interest treatment or repayment strategy differs. For investment-related purposes, your accountant should advise on tax deductibility and record keeping. Do not assume interest is deductible simply because your property is an investment property. The use of the borrowed funds is generally critical.
For business owners, separating personal and business-related borrowing can also make accounting clearer. It may be appropriate to consider a residential cash-out refinance, a commercial facility, asset finance or a combination, depending on the security available and what the funds are intended to achieve.
Costs and risks to consider before refinancing
A refinance should be assessed against the full picture, not only the new interest rate. There can be discharge fees, application fees, valuation costs, government charges and lender mortgage insurance at higher LVRs. If you are leaving a fixed loan, break costs may apply and can be substantial.
There is also the risk of securing previously unsecured debts against your home. If repayments are not maintained, your property is at risk. That does not mean refinancing is the wrong decision, but it does mean the loan amount and repayment should leave room for rate rises, quieter business periods and unexpected household costs.
A good assessment considers whether the new facility will improve your position in six months as well as on settlement day. Sometimes the best solution is to reduce the cash-out amount, use a different security structure or stage a business or renovation project rather than borrowing the maximum available.
A specialist pathway for complex borrowers
Borrowers are often declined because their application has been assessed under a policy that does not fit their circumstances. That is particularly common for self-employed applicants, clients with a recent credit issue, older borrowers, contractors, expatriates and people with non-standard income.
Finance Me helps clients present the full story to lenders that can consider alternative documentation, adverse credit and more complex servicing profiles. The process starts by reviewing the property, current debts, income evidence, credit position and the exact purpose of the cash out. From there, the loan can be structured around realistic borrowing capacity rather than a generic bank calculator.
If you are considering a refinance, gather recent loan statements, rates notices, income documents, bank statements and payout figures for debts you want to clear. Clear information gives you a stronger starting point and helps identify a lending option that supports what you need to do next.