A bank decline can make it feel as though the door has closed on buying, refinancing or funding your business. Often, it has only closed with that particular lender. The choice between a mortgage broker versus direct lender matters most when your income, credit history or loan purpose sits outside a major bank’s standard policy.
A direct lender can be a sensible option when your circumstances are straightforward and its product suits you. A specialist broker can be more valuable when the application needs to be positioned carefully, supported with alternative evidence or matched to a lender that understands the reason behind the numbers.
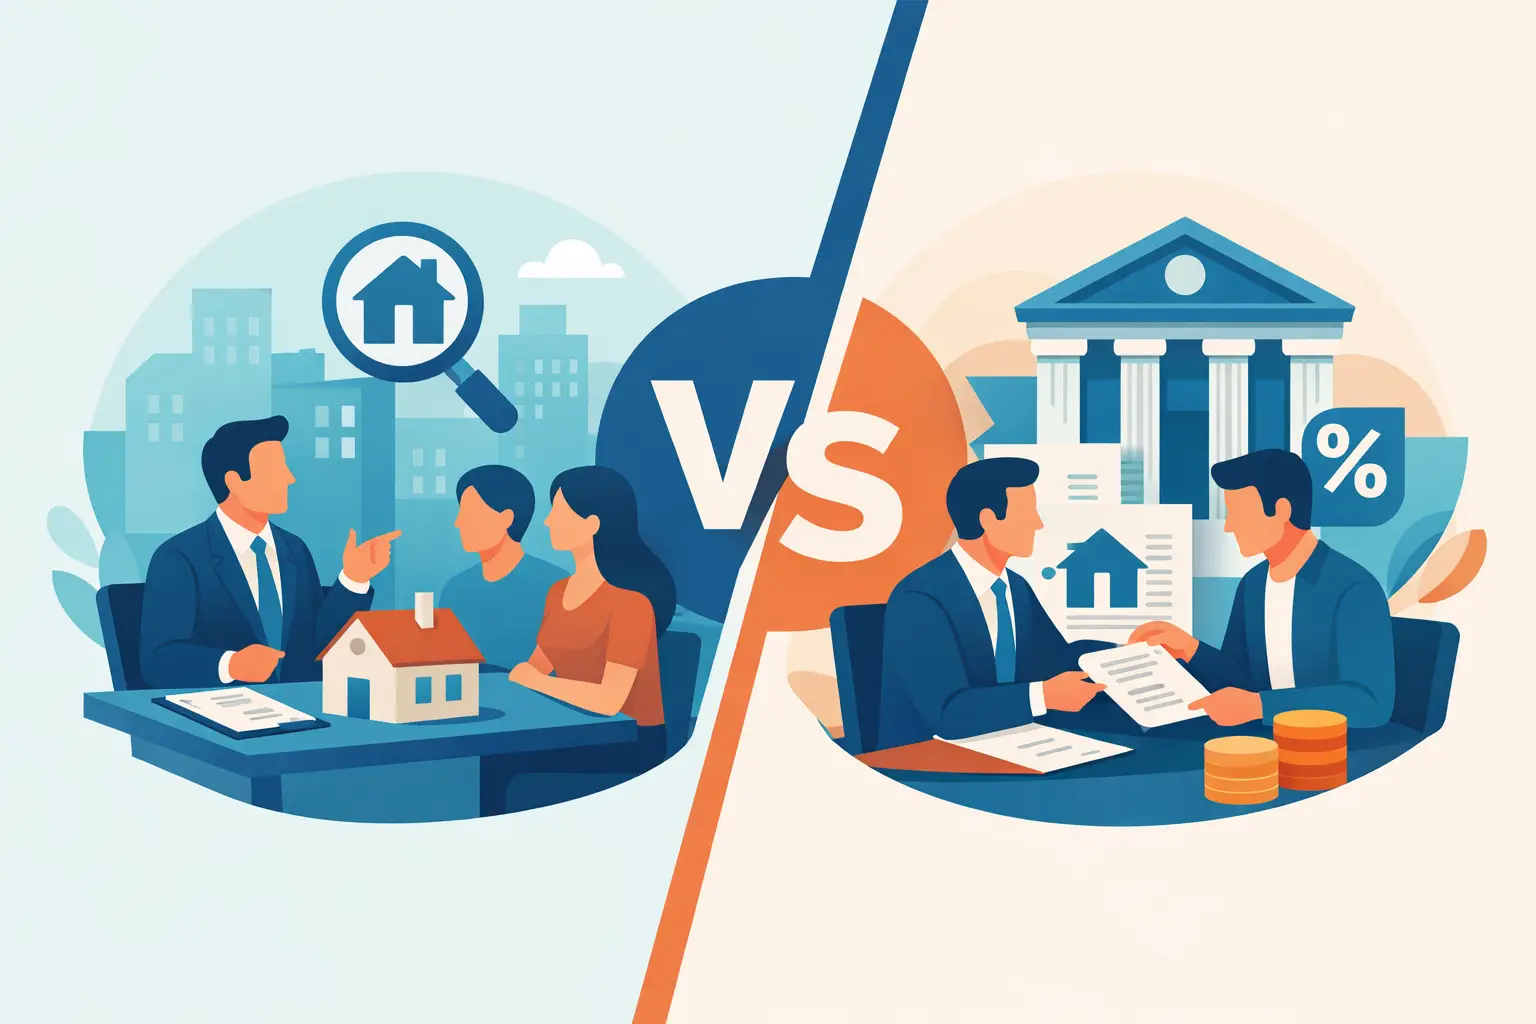
Mortgage broker versus direct lender: the key difference
A direct lender is the organisation providing the loan. This could be a major bank, non-bank lender, credit union or specialist funder. When you apply directly, that lender assesses your application against its own credit policy, servicing rules, acceptable income types and property requirements. Its staff can explain its products, but they cannot offer a loan from outside their own range.
A mortgage broker acts as an intermediary between you and a range of lenders. The broker reviews your position, identifies lenders whose policies may fit, prepares the application and manages communication through approval and settlement. The quality of that work is particularly important where a loan is not a clean, standard application.
Neither route is automatically better. The right choice depends on whether the lender you approach can genuinely assess your situation on its merits, and whether you know which policy is likely to work before applying.
When going direct can make sense
Applying to a direct lender may suit an owner-occupier with stable PAYG income, a strong credit file, a reasonable deposit and a simple property purchase. If you already bank with that lender, you may also value dealing with one institution or have access to a particular package, relationship discount or existing customer offer.
Going direct can also be practical when you have compared the available terms and are confident the lender’s policy fits. For example, a borrower with two years in the same permanent role, clear repayment history and conventional income may not need a specialist pathway.
The limitation is that a direct lender can only say yes or no under its own rules. A decline may arise from a policy setting rather than an inability to afford the loan. Common examples include a lender refusing overseas income, requiring a longer employment history, excluding a recent paid default, or declining a self-employed applicant whose taxable income has been reduced by legitimate business expenses.
A decline itself can also create pressure. Multiple credit enquiries in a short period are not always fatal, but they can complicate the story if applications have been made without a clear strategy.
Where a specialist broker can add real value
A broker is not simply someone who fills out an application form. For complex borrowers, the work starts with understanding why a mainstream lender may have said no and whether there is a suitable alternative.
That may involve matching a client with a lender that accepts alt-doc income verification, considers BAS statements and business bank statements, or takes a more flexible view of non-standard employment. It may mean finding a policy that can consider discharged bankruptcy, paid defaults or a completed Part 9 debt agreement, subject to the lender’s criteria and the overall strength of the application.
For a company director, the right lender may assess income differently from the bank where the business holds its transaction account. For an Australian earning overseas income, currency, employment type and tax documentation may need careful treatment. For a medical professional, lender policy around training, contracts or professional income can make a material difference.
Finance Me works with borrowers who have been knocked back or do not fit conventional lending boxes. That includes residential, commercial, asset finance, refinance and debt-consolidation applications where the lender choice, evidence and application presentation all need more attention than a standard bank form allows.
More choice does not mean every option is right
Broker access to multiple lenders is useful, but it should not be confused with an automatic approval or a reason to borrow more than is comfortable. Each lender has its own risk appetite, pricing, fees, valuation approach and documentation requirements.
Specialist loans can carry a higher interest rate or fee structure than prime bank lending. That can be appropriate where the lender is accepting a higher-LVR purchase, adverse credit history, alternative income documents or a complex security arrangement. However, the cost needs to be weighed against the opportunity. A borrower may use specialist finance to purchase now, consolidate unmanageable debt or refinance away from an unsuitable arrangement, then review the loan later when their credit profile or financial position improves.
A good broker should explain the trade-off plainly. The question is not only, “Can I get approved?” It is also, “Is this loan suitable for my current needs, and what is the plan from here?”
Approval policy is not the same as affordability
This distinction is easy to miss after a bank decline. Lenders use servicing calculations that factor in income, expenses, existing debts, dependants, interest-rate buffers and the proposed loan repayment. Their methods vary. One lender may shade overtime heavily, while another may accept a portion with sufficient history. One may require two years of tax returns from a self-employed borrower, while another may accept alternative documentation for an eligible loan.
That does not remove the need for a realistic budget. A loan should remain manageable if rates rise, income fluctuates or business trading has a slower month. It does mean that a borrower with genuine repayment capacity should not assume a single rejection is a final verdict.
The same principle applies to credit issues. A low credit score, late payment or historic hardship event will affect lender options. But context matters. Was the issue paid? How long ago did it occur? Was it linked to a one-off event, separation, illness or a business disruption? Has the applicant since demonstrated stable conduct? Specialist lenders may assess that picture differently, though no responsible lender will ignore current affordability or unresolved liabilities.
Documentation can determine the lender pathway
Direct applications tend to work best when you can meet the lender’s requested documents exactly. A broker can help identify what evidence may be accepted before the application is submitted.
For PAYG borrowers, this may include payslips, employment contracts, group certificates or account statements showing salary credits. Self-employed applicants may need tax returns, notices of assessment, BAS statements, accountant letters and business bank statements. Those receiving foreign income may require employment evidence, bank statements, tax records and currency conversion details.
For adverse-credit applications, clear evidence of paid defaults, discharge documents, debt-agreement completion information and explanations for past events can be important. Providing documents early does not guarantee approval, but it helps avoid delays and gives the lender a complete basis to assess the application.
Questions to ask before choosing either route
Whether you speak to a lender or broker, ask how your income will be treated, what credit events are acceptable and what deposit or equity is required. Ask about the comparison rate, establishment and ongoing fees, valuation costs, redraw or offset availability, repayment flexibility and any break costs if the loan is fixed.
For a property purchase, ask whether the proposed security meets the lender’s requirements and whether lenders mortgage insurance may apply. Eligible borrowers may be able to access high-LVR lending up to 95%, but the maximum available will depend on the property, purpose, income, credit profile and lender policy.
For refinance or debt consolidation, ask what debts will be paid out, whether the new repayment is sustainable, and whether extending the loan term changes the total cost over time. Consolidation can create breathing room, but it needs a clear plan so short-term debt does not simply build up again.
A practical way to decide
If your application is conventional, you have identified a competitive direct product and you meet the lender’s policy, applying direct may be efficient. If there is a policy issue, unusual income, a recent credit event, a high-LVR requirement or a larger commercial transaction, a specialist broker can reduce guesswork by assessing lender fit before applications are lodged.
The best starting point is an honest review of your position: your income evidence, debts, credit history, deposit or equity, property type and reason for borrowing. There is no shame in needing a different lending pathway. The useful next step is finding one that is realistic, clearly explained and built around your ability to move forward with confidence.